
Bitcoin Mining Dashboard
Daily Network Data (30 October – 4 November 2026)
BTC Production & Miner Revenue
Bitcoin Mining Pools
Top 5 Bitcoin Mining Countries
Top 5 Mineable Proof-of-Work Coins
Mining Cost & Profitability
ASIC Economics
ICR View: Last Week’s Calls, Outcomes & Next Week’s Outlook

Hashrate eased for the first time in this series, averaging ~1,059 EH/s (−2.3% week over week) and ending the week at 1,029 EH/s.
Blocks slowed to ~140.5 per day, 2.4% below target, so miners earned 2,634.4 BTC (~$204M) in six days, about 439 BTC/day versus ~490 last week.
Difficulty held at 148.36T all week; the 12 November retarget is now estimated at only +1.87%, well below the +4.8% early estimate.
Hashprice averaged ~$32.13/PH/day, the lowest weekly average in this series, before BTC’s rebound to ~$80.4K lifted it to $34.28 on 5 November.
 Part of a series
Hashrate paused after two straight difficulty increases. It averaged about 1,059 EH/s, down 2.3% from ~1,084 EH/s, and slid from 1,078 EH/s on 1 November to 1,029 EH/s on 4 November, slightly below the ~1,062 EH/s needed for 10-minute blocks at 148.36T. Because of this, blocks arrived slightly late for the first time in this series. About 843 blocks were found in six days (~140.5 per day, a ~10.2-minute average), 2.4% below target, producing 2,634.4 BTC (~$204 million).
BTC’s average price was ~$77.5K, down about 4% from last week, and the realised hashprice averaged ~$32.13/PH/day, down 12% and the lowest weekly figure we have recorded. BTC rebounded to ~$80.4K on 5 November, lifting Hashrate Index’s hashprice to $34.28, and the 12 November retarget is now projected at only +1.87%, much smaller than the last two.
Metric | This week (30 Oct–4 Nov) | Comment |
|---|---|---|
BTC price | ~$77.5K avg. (~$80.4K on 5 Nov) | Average of daily closes, $76.7K–$78.3K; down ~4.1% WoW; rebounded on 5 Nov |
Network hashrate | ~1,059 EH/s avg. | Daily range 1,029–1,078 EH/s; down ~2.3% from ~1,084 last week |
Mining difficulty | 148.36T (unchanged all week) | Set at block 973,728 on 29 Oct (+5.54%) |
Hashprice | ~$32.13 avg. (~$34.28 on 5 Nov) | Weekly realised average, down ~12%; Hashrate Index on 5 Nov |
Blocks found | ~843 (~140.5/day) | 2.4% below the 864-block target; ~10.2-min average block time |
BTC block subsidy mined | 2,634.4 BTC (6 days) | Blocks found × 3.125 BTC; ~439 BTC/day |
Transaction fees (est.) | ~16 BTC | ~0.60% of block reward (Hashrate Index pool data) |
Next difficulty adjustment | ~+1.9% to ~151.1T | Block 975,744, est. ~12 Nov; 901 of 2,016 blocks mined (CoinWarz, 5 Nov) |
Estimated production cost | ~$61.2K/BTC | At 148.36T; 18 J/TH and $0.06/kWh |
Date | Day | Hashrate (EH/s) | BTC price ($) | Hashprice ($/PH/day) | Difficulty (T) | Blocks | Subsidy (BTC) | BTC mined |
|---|---|---|---|---|---|---|---|---|
30-Oct-26 | Friday | 1,070 | 77,720.62 | 31.10 | 148.36 | 137 | 3.125 | 428.13 |
31-Oct-26 | Saturday | 1,066 | 77,241.96 | 32.61 | 148.36 | 144 | 3.125 | 450.00 |
01-Nov-26 | Sunday | 1,078 | 77,420.90 | 32.99 | 148.36 | 147 | 3.125 | 459.38 |
02-Nov-26 | Monday | 1,065 | 78,298.85 | 34.00 | 148.36 | 148 | 3.125 | 462.50 |
03-Nov-26 | Tuesday | 1,044 | 76,693.15 | 29.16 | 148.36 | 127 | 3.125 | 396.88 |
04-Nov-26 | Wednesday | 1,029 | 77,404.59 | 32.91 | 148.36 | 140 | 3.125 | 437.50 |
Week | Total / avg. | 1,059 avg. | 77,463 avg. | 32.13 avg. | 148.36 | 843 | 3.125 | 2,634.39 |
Hashrate, BTC price, blocks and BTC mined are from ICR’s daily tracking sheet. Hashprice is realised subsidy revenue per PH/s (BTC mined × BTC price ÷ hashrate in PH/s) and excludes fees. Difficulty stayed at 148.36T, set late on 29 October, for the whole week.
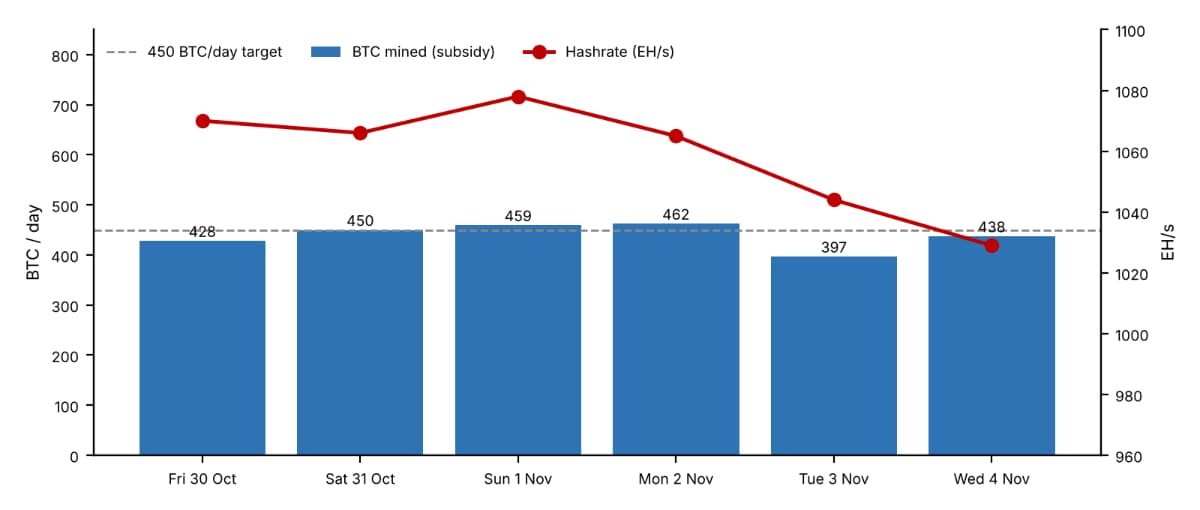
Daily BTC mined (bars) against network hashrate (line). The dashed line marks the 450 BTC/day target at 144 blocks/day.
This was the first week in this series with output below target. Hashrate eased from 1,078 EH/s on 1 November to 1,029 EH/s on 4 November, about 3% below the ~1,062 EH/s needed for 10-minute blocks. Three of the six days fell short of the 450 BTC target. Tuesday 3 November was the weakest, with 127 blocks and 396.88 BTC (~12% below target) and a realised hashprice of $29.16, the lowest daily hashprice we have recorded.
BTC production over the six days came to 2,634.4 BTC, or about 439 BTC per day. That is ~10% less per day than last week (~490 BTC/day). Difficulty had risen 5.54% on 29 October and hashrate fell about 2%, so block production dropped from about 157 to about 140.5 per day. On a 7-day basis, this pace equals roughly 3,070 BTC. Fees rose slightly to about 0.6% of the block reward.
Component | Weekly BTC (6 days) | Approx. share of block subsidy |
|---|---|---|
Block subsidy | 2,634.4 BTC | 100% |
Transaction fees (est.) | ~16 BTC | ~0.60% |
Approx. USD value of subsidy | ~$204M | At each day’s BTC price (avg. ~$77.5K) |
Rank | Mining pool | Blocks | Approx. hashrate (EH/s) | Approx. share |
|---|---|---|---|---|
1 | Foundry USA | 243 | 254.73 | 24.87% |
2 | AntPool | 195 | 204.41 | 19.96% |
3 | F2Pool | 169 | 177.16 | 17.30% |
4 | ViaBTC | 96 | 100.63 | 9.83% |
5 | SpiderPool | 54 | 56.61 | 5.53% |
6 | MARA Pool | 51 | 53.46 | 5.22% |
7 | OCEAN | 48 | 50.32 | 4.91% |
8 | Luxor | 45 | 47.17 | 4.61% |
9 | SECPOOL | 35 | 36.69 | 3.58% |
10 | Braiins Pool | 12 | 12.58 | 1.23% |
11 | CloverPool | 10 | 10.48 | 1.02% |
12 | TrustPool | 9 | 9.43 | 0.92% |
13 | Unknown | 7 | 7.34 | 0.72% |
14 | Poolin | 2 | 2.10 | 0.20% |
15 | Binance Pool | 1 | 1.05 | 0.10% |
| All miners | 977 | 1,024.16 | 100% |
Pool block counts, hashrate and shares as compiled by ICR from block-attribution data on 5 November 2026 (977-block sample).
Over the week, total pool hashrate fell about 3.0% to ~1,024 EH/s (from ~1,056 EH/s), and concentration eased. The top three pools found 62.1% of blocks (64.0% last week), and the top five found 77.5% (78.5% last week). Foundry USA lost 1.5 points to 24.9%, and AntPool lost 0.7 points to 20.0%, while ViaBTC gained 0.9 points to 9.8%. SpiderPool returned to fifth at 5.5% (+1.1 points), OCEAN rose to 4.9% (+1.2 points), and Luxor slipped to eighth at 4.6% (−1.0 points). Binance Pool found just one block (0.1%), and two pools new to our list appeared: CloverPool (1.0%) and TrustPool (0.9%). There were three empty blocks, two from OCEAN and one from ViaBTC.
Last week, we expected Binance Pool’s miners to lift the big FPPS pools and push the top five toward 79–80%. Binance Pool has indeed almost emptied (from 0.85% to 0.1%), but the largest pools lost share instead of gaining it, so that call missed. Block data cannot show where individual miners went. CloverPool and TrustPool, together ~1.9% of blocks, are one possible destination, but we cannot confirm it. With Binance Pool already close to zero, its 10 November closure should have little further effect, and we now expect the top five to stay in a 77–79% range. OCEAN’s two empty blocks and lower health score (95.9%) are worth monitoring, but they are too few to signal a problem.
Rank | Country | Approx. share | Approx. hashrate |
|---|---|---|---|
1 | United States | 35.6% | ~377 EH/s |
2 | Russia | 18.1% | ~192 EH/s |
3 | China | 11.7% | ~124 EH/s |
4 | Paraguay | 4.8% | ~51 EH/s |
5 | Oman | 3.0% | ~32 EH/s |
Shares from the Hashrate Index Q4 2026 Global Hashrate Heatmap (unchanged); hashrate implied by applying each share to ~1,059 EH/s.
Coin | Algorithm | Price | Difficulty | Network hashrate | Key mining characteristic |
|---|---|---|---|---|---|
BTC | SHA-256 | $80,400.30 | 148.36T | 995.7 EH/s | Largest PoW network; halving-driven subsidy |
ZEC | Equihash | $1,323.33 | 262.57M | 31.35 GH/s | Privacy-focused PoW asset |
DOGE | Scrypt | $0.08 | 46.15M | 3.146 PH/s | High issuance; merged-mined with LTC |
XMR | RandomX | $635.22 | 855.58B | 7.13 GH/s | CPU-friendly, ASIC-resistant privacy coin |
BCH | SHA-256 | $282.51 | 527.24B | 4.225 EH/s | Shares SHA-256 mining ecosystem with BTC |
Compared with the 30 October snapshot, XMR rose about 8.5% to ~$635, with its network hashrate and difficulty both up about 15.5%. ZEC rose about 5.8% to ~$1,323, and BTC about 2.8% to ~$80.4K. DOGE network hashrate rose about 12% to ~3.1 PH/s, and BCH hashrate rose about 6% to ~4.2 EH/s.
The table below shows estimated electricity-only production costs at the current 148.36T difficulty, and at the ~151.1T estimated for the 12 November retarget.
Scenario | Electricity / efficiency | Cost at 148.36T (now) | Cost at ~151.1T (est.) |
|---|---|---|---|
Efficient operation | $0.05/kWh, ~12 J/TH | ~$34K | ~$35K |
Mid-case | $0.06/kWh, ~18 J/TH | ~$61K | ~$62K |
Older fleet | $0.06/kWh, ~35 J/TH | ~$119K | ~$121K |
The mid-case cost stayed at ~$61.2K per BTC this week. At the week’s average BTC price of ~$77.5K, the mid-case gross spread was about 21% of price, in line with the ~22% we expected. BTC’s rebound to ~$80.4K on 5 November lifts that to about 24%. A ~+1.9% retarget on 12 November would raise the mid-case cost to ~$62.3K and trim the spread at $80.4K to about 22.5%. This is not corporate net profit: debt service, depreciation, hosting, staff, maintenance, SG&A and financing costs are excluded.
Indicator | What to track each week |
|---|---|
ASIC hashrate | TH/s per machine |
Energy efficiency | J/TH |
Power consumption | kW per machine |
Revenue | BTC/US$ per day (≈0.000424 BTC per PH/s/day at 148.36T) |
Electricity expense | US$/day at selected tariff |
Gross mining margin | Revenue less electricity |
ASIC payback | Months at current economics |
As a rule of thumb, at this week’s average realised hashprice of ~$32.13/PH/day, an ASIC covered its electricity when tariff × J/TH was below about 1.34 (for example, $0.06/kWh × ~22 J/TH). At 5 November’s $34.28, the threshold is about 1.43 ($0.06/kWh × ~24 J/TH). With BTC flat, a ~+1.9% retarget would trim it to about 1.40 (~23 J/TH).
Our call (24–29 Oct report) | What happened (30 Oct–4 Nov) | Verdict |
|---|---|---|
Difficulty: unchanged; 12 Nov retarget +2% to +5% | Unchanged at 148.36T; 12 Nov estimate now +1.87% | Close (just below range) |
Hashprice: ~$32–35; base ~$33–34 at ~$78K BTC | Realised avg $32.13 at ~$77.5K BTC; $34.28 on 5 Nov | Correct (low end) |
Hashrate: level off at ~1,060–1,100 EH/s | Avg ~1,059 EH/s; slid from 1,078 to 1,029 | Partly right |
Issuance: ~147 blocks/day, ~3,200 BTC/week | ~140.5 blocks/day; ~3,070 BTC 7-day pace | Too high |
Margins: mid-case spread ~22% at ~$78K BTC | ~21% at the ~$77.5K average | Correct |
Scorecard: two calls were right (hashprice and margins), two were close (difficulty and hashrate) and two missed (issuance and pool concentration, covered in the Pool outlook). The misses trace to hashrate easing instead of holding, and to Binance Pool’s miners not visibly moving to the largest pools.
• Difficulty: No change until the retarget at block 975,744, estimated for 12 November. CoinWarz puts it at +1.87% to ~151.1T, with about 45% of the difficulty cycle mined. With hashrate ending the week near 1,030 EH/s, below the ~1,062 EH/s needed for 10-minute blocks, we expect slightly less: a range of 0% to +2%, with a base case of about +1%.
• Hashprice: Each $1,000 move in BTC shifts hashprice by about $0.43/PH/day. With BTC between $78K and $82K, we expect hashprice of ~$33–35 before the retarget, and roughly $0.50 lower after a +1–2% increase. Base case ~$34.
• Hashrate: We expect ~1,030–1,070 EH/s. Hashrate Index’s forward curve implies about 1,056 EH/s for November, a pause rather than a climb or a sharp exit.
• BTC issuance: With hashrate just below the ~1,062 EH/s needed for 10-minute blocks, we expect ~142 blocks a day, about 445 BTC a day, or ~3,100 BTC for the week.
This week looked like a pause, not a capitulation. After two increases in two weeks (+5.92% and +5.54%), hashrate pulled back about 2% to ~1,059 EH/s, blocks slowed below target for the first time in this series, and a ~4% lower BTC price (average ~$77.5K) pushed the realised hashprice down to ~$32.13, our lowest weekly average. BTC’s rebound to ~$80.4K on 5 November has since lifted hashprice to $34.28. Our prediction for next week: a retarget of about +1% (range 0% to +2%) around 12 November, hashprice of ~$33–35, hashrate of 1,030–1,070 EH/s and about 3,100 BTC of issuance.
Sources: ICR daily tracking sheet (30 Oct – 4 Nov 2026), Hashrate Index (5 Nov), CryptoSlate (4 Nov), CoinWarz, ICR pool data (5 Nov) and Minerstat.
India Crypto Research operates independently. The information presented herein is intended solely for educational and informational purposes and should not be construed as financial advice. Before making any financial decisions, it's essential to undertake your own thorough research and analysis. If you're uncertain about any financial matters, we strongly recommend seeking guidance from an impartial financial advisor.


